

GLOBAL ECONOMICS AND POLITICS

Leo Haviland provides clients with original, provocative, cutting-edge fundamental supply/demand and technical research on major financial marketplaces and trends. He also offers independent consulting and risk management advice.

Haviland’s expertise is macro. He focuses on the intertwining of equity, debt, currency, and commodity arenas, including the political players, regulatory approaches, social factors, and rhetoric that affect them. In a changing and dynamic global economy, Haviland’s mission remains constant – to give timely, value-added marketplace insights and foresights.

Leo Haviland has three decades of experience in the Wall Street trading environment. He has worked for Goldman Sachs, Sempra Energy Trading, and other institutions. In his research and sales career in stock, interest rate, foreign exchange, and commodity battlefields, he has dealt with numerous and diverse financial institutions and individuals. Haviland is a graduate of the University of Chicago (Phi Beta Kappa) and the Cornell Law School.


Subscribe to Leo Haviland’s BLOG to receive updates and new marketplace essays.

RSS View Leo Haviland's LinkedIn profile View Leo Haviland’s profile



ECONOMIC AND POLITICAL LINES (c) Leo Haviland October 22, 2012

Highlight two International Monetary Fund comments in its recently unveiled “Fiscal Monitor” (October 2012). “With downside risks in the global economy mounting, policymakers must once again tread the narrow path that will permit them to continue strengthening the public finances while avoiding an excessive withdrawal of fiscal support for a still-fragile economic recovery.” (page ix). And: “In most advanced economies, the near-term fiscal stance has to walk the fine line between continued adjustment and supporting the economy.” (p6).

This IMF rhetoric, which many other luminaries embrace, of “tread the narrow path” and “walk the fine line” offers hope for the global economy and for the United States in particular. Maybe subtle financial and political sorcerers somehow can escape the dilemma of an economic downturn (too slow growth or recession) and the consequences of additional (irresponsible) substantial deficit spending! Have faith that wise guardians can discover a middle way to evade further suffering!

In the amazing Goldilocks Era, didn’t substantial and growing worldwide debt and leverage joyously promise and provide nearly limitless opportunity for almost everyone (“us”) to prosper with very little (or at least manageable) risk? In the aftermath of the wonderful Goldilocks epoch, should we believe that the implications of significant leverage and mountainous debt accumulation can be magically pain-free, at least over some misty medium term or long run vista?

Despite such entrancing sermons of narrow paths and fine lines from many respected central banking and political guides, economic and political pilgrims should ask if such a path or line exists in practice. It probably doesn’t. Is there really a way for the United States to avoid the looming fiscal cliff and other long run deficit challenges without significant hardship? Probably not.

Most observers are not focusing closely on the potential composition of the Senate. They should. The Senate election result probably will have notable consequences for legislative action (or inaction) in many domains. For example, think of the troubling fiscal cliff and the terrifying long run deficit problems.

Clairvoyants on balance believe the Democrats probably will maintain control of the Senate. Even if the Republicans gain an edge in the Senate, it would be very surprising for them to capture anything close to 60 seats. According to Senate rules, to end debate (halt filibusters) on a legislative proposal (bill), 60 of the 100 Senators must agree to do so (invoke cloture). The sixty votes do not have to all be from the same party. Nevertheless, the failure of a Senate majority party to control 60 or more Senate seats means that its opponents generally can block the majority party’s legislative efforts.

So suppose the House is Republican, and the Senate is Democratic (or even imagine a modest Republican majority). Given such Congressional division, it will be a major challenge for the parties to readily resolve issues over which they disagree dramatically, such as on how to repair the federal deficit disaster. In that situation, the party membership of the winner of the duel for the Presidency matters much less. After all, for the past several years, the Republican House and the Democratic Senate stubbornly have faced each other. With these battle lines, there has been at best little progress on reducing the deficit. Why should having a Republican President instead of a Democratic one change this partisan deadlock in any notable fashion?

FOLLOW THE LINK BELOW to download this market essay as a PDF file.
Economic and Political Lines (10-22-12)
Chart- Commodities- Broad GSCI (10-22-12)
AMERICAN MARKETPLACES: AT THE CROSSROADS © Leo Haviland October 15, 2012

The world’s long-running economic crisis of course has not limited itself to either one nation or one region. However, at its outset in 2007, most did not anticipate the scope or length of the disaster. Weren’t potential risks to the international economy rather modest? Weren’t issues related to the United States real estate marketplace mostly relevant only to that domain and that nation, and likely to be restricted to them? Yet substantial debt and leverage (and other intertwined issues) and their consequences were not confined either to American territory or the real estate playground.

The recent Eurozone chapters of this terrible trouble supposedly started with so-called peripheral nations such as Greece, Portugal, and Ireland. Countries such as Greece indeed first captured headlines. However, that does not demonstrate that causes of Eurozone problems necessarily started only in them. In any event, “difficulties on the periphery” engulfed the rest of Europe and traveled around the globe.

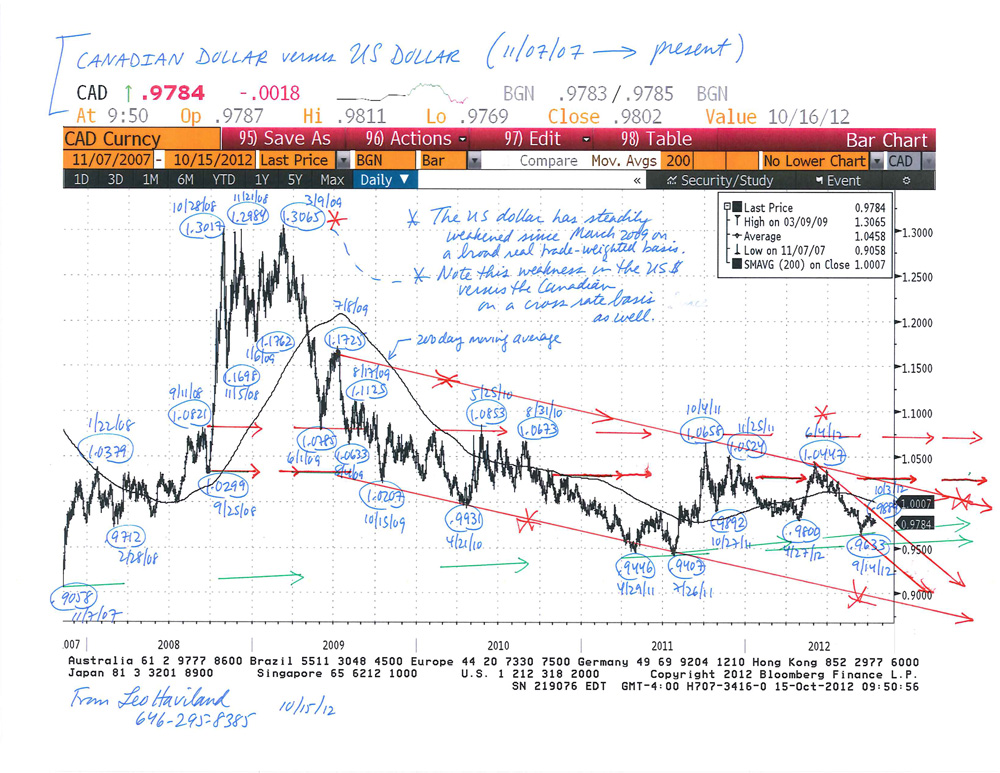
Despite broad concerns regarding worldwide economic problems and risks, despite the widespread past and current fascination with the European scene, suppose one focuses on aspects of the American stage, beginning with some highlights involving the United States alongside Canada and Mexico in the foreign exchange context. This survey of America and its geographic neighbors underlines the weakness of the United States dollar and the size of America’s fiscal troubles. This suggests the merit of inquiring into US currency, stock, interest rate, and commodity marketplace past and future relationships in the context of Federal Reserve easing policies and America’s fiscal problems.

The broad real trade-weighted dollar probably will continue to weaken. The dangerous United States fiscal situation probably will not be genuinely fixed in the next several months. A full- fledged threat of a federal fiscal catastrophe likely will be necessary for sufficient progress in that sphere to occur. Though the United States is not the center of the universe, the effects of further dollar feebleness and the worsening of the country’s fiscal crisis will radiate worldwide.

The S+P 500 has made or soon will make a significant peak.

Thus the emerging (current) story and trend appears to be: weaker dollar (TWD), weaker S+P 500, and higher government rates (UST 10 year benchmark). This vision admittedly is dramatically different from the current popular faith in these marketplace relationships.


FOLLOW THE LINK BELOW to download this market essay as a PDF file.
American Marketplaces- At the Crossroads (10-15-12)
Charts- US Dollar v Canadian Dollar, Mexican Peso (10-15-12)

FED FIXATIONS: INTEREST RATES © Leo Haviland September 24, 2012

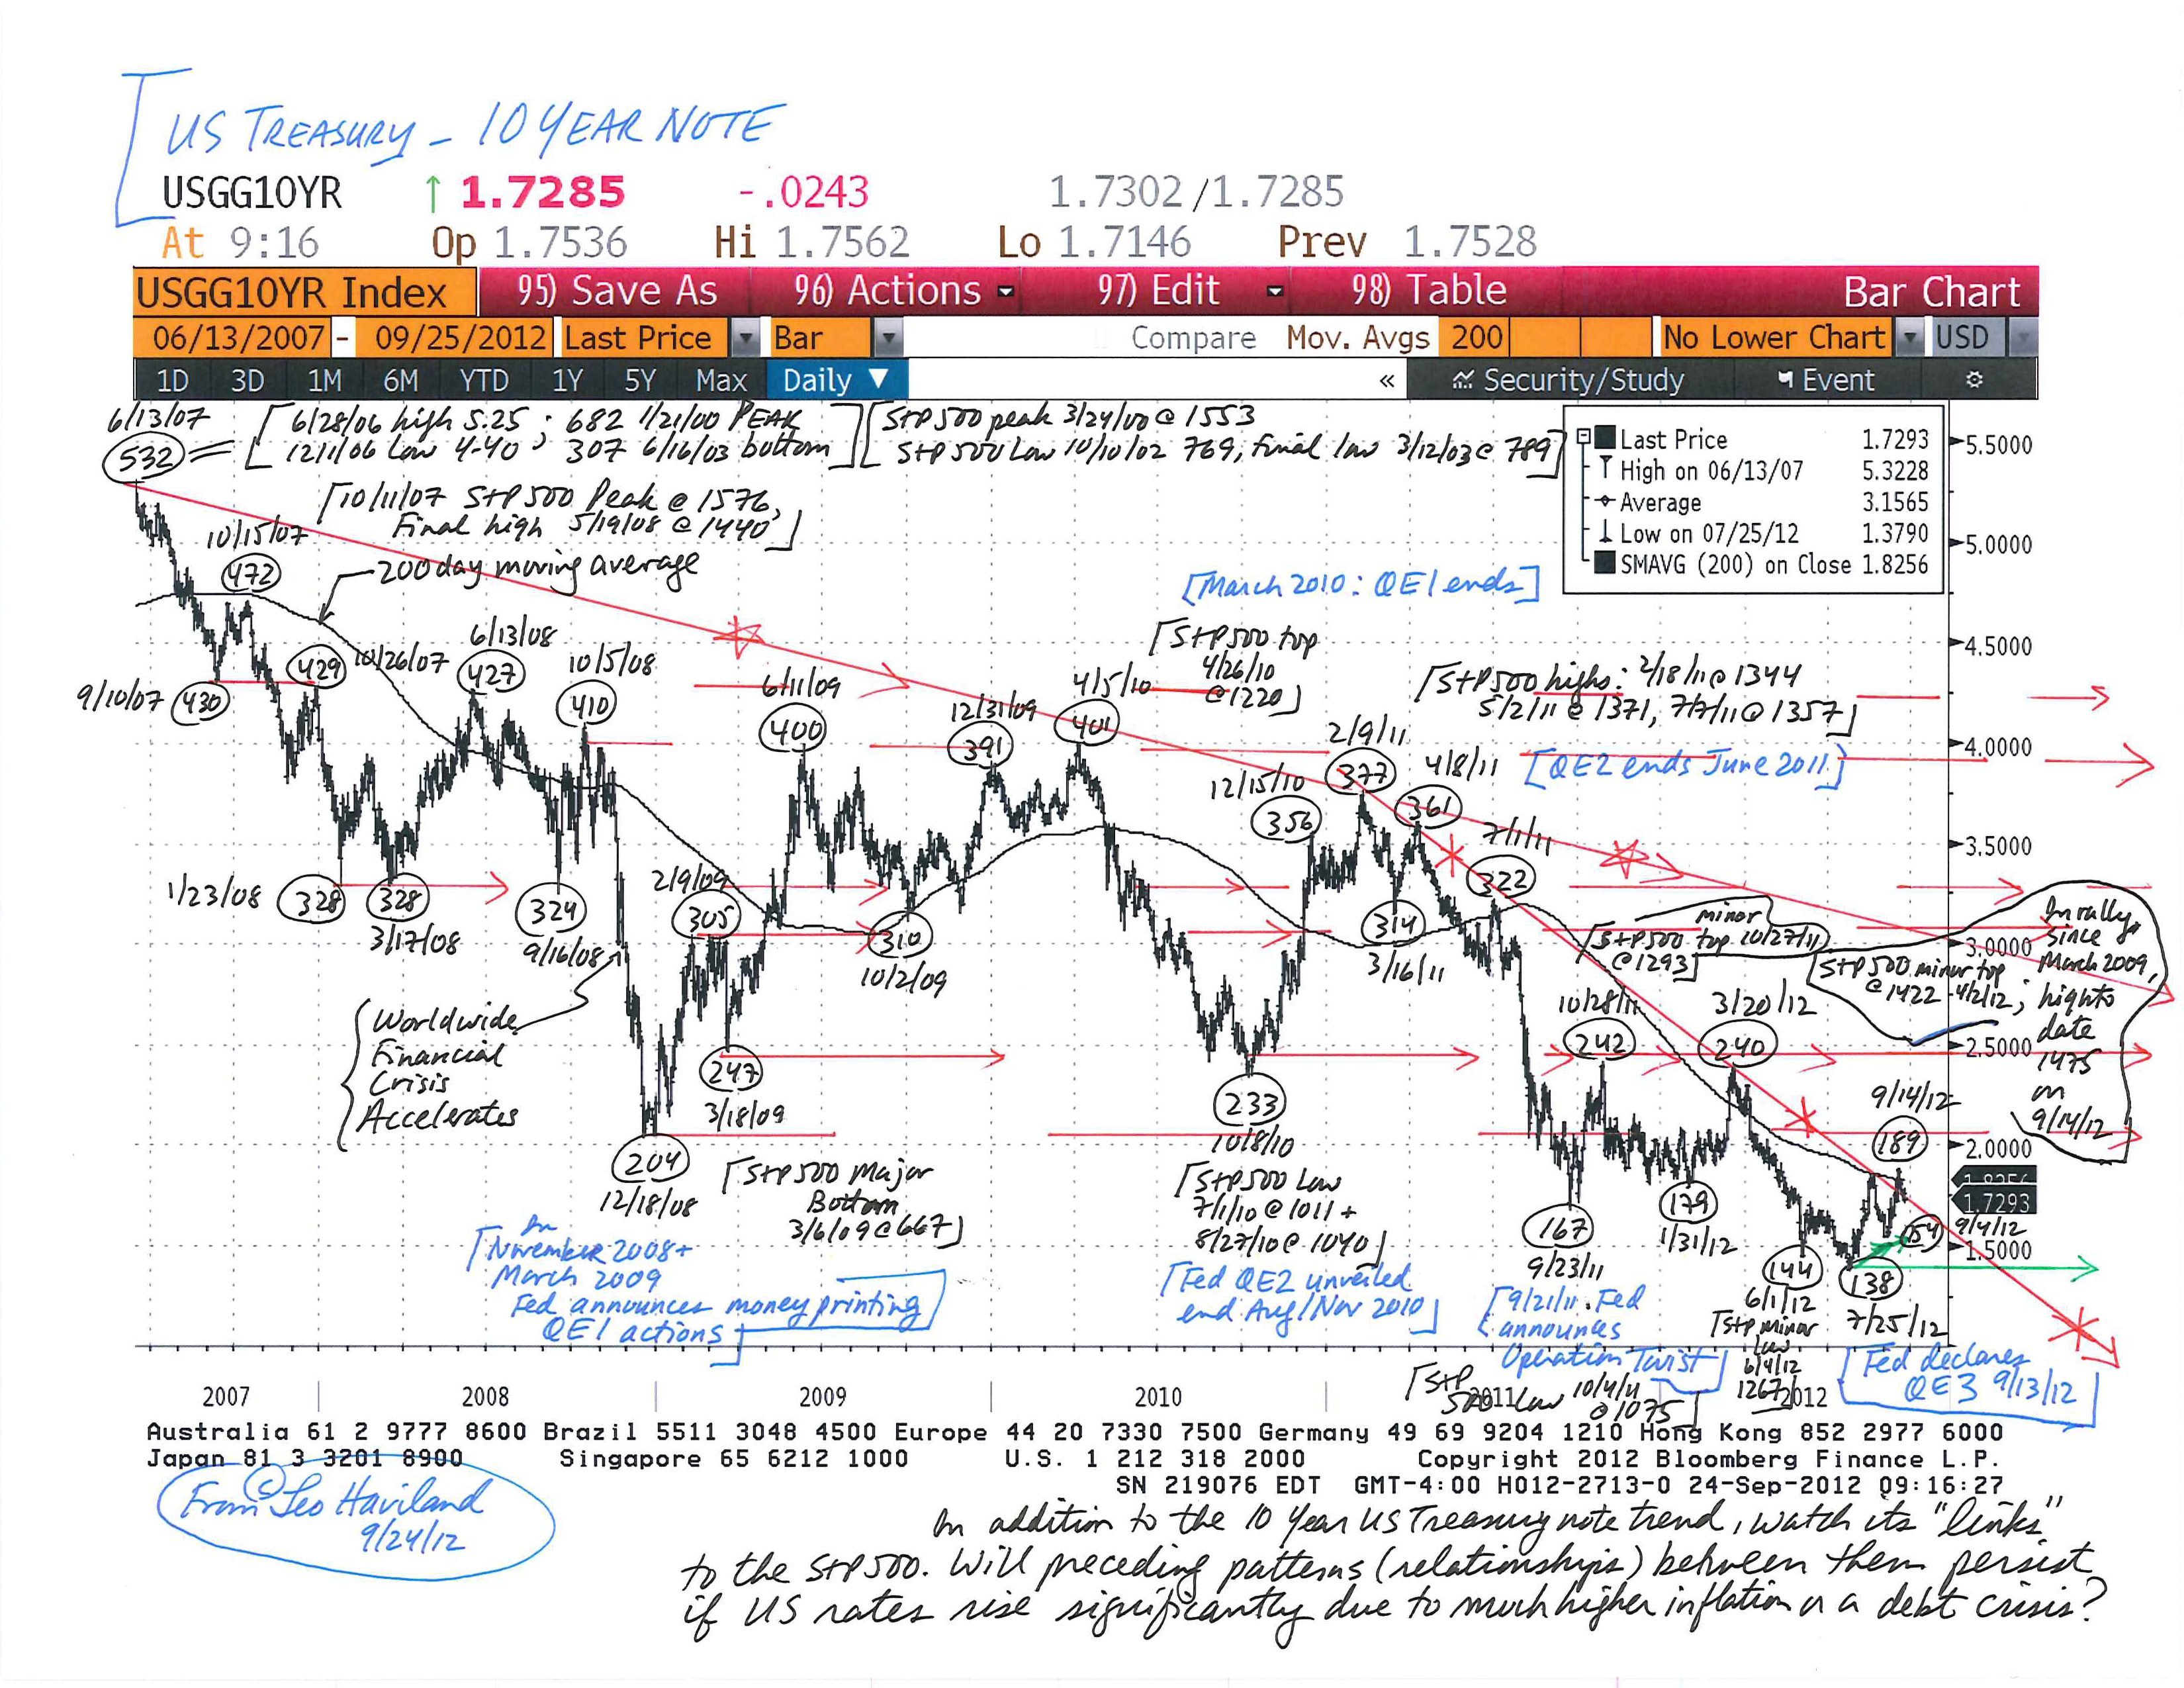
A key United States interest rate benchmark, the 10 year Treasury note, probably established a major bottom around 1.40 percent in late July 2012.

The Federal Reserve Board’s fixing of the Federal Funds rate at exceptionally low levels admittedly restrains ascents in US government yields. Its benevolent promise and determination to maintain the Funds rate almost flat on the ground until at least mid-2015 encourages faith that government yields generally will remain depressed. Also, heightened flight to quality fears and nervous leaps in recessionary worries may push the 10 year UST challenge back toward or even slightly beneath its July low. The Eurozone crisis, for example, has not disappeared. America’s 2013 federal “fiscal cliff” looms large on the horizon.

However, all else equal, a flood of money printing tends to increase inflation and thus interest rates. And all else equal, cracking or crumbling creditworthiness for a borrower- whether an individual, corporation, or government- tends to boost the interest rate charged that borrower. America nowadays confronts another round of Federal Reserve money printing and has made little headway in resolving its awesome fiscal problems.

The Federal Reserve’s long rumored (fervently hoped for) and recently decreed (9/13/12) third cascade of money printing, QE3, probably will be massive, perhaps over one trillion dollars. Over time, this deluge will help to boost US government (and other) interest rates.

Moreover, given a generous desire to avoid the fiscal cliff and a downturn, Congress probably will continue its huge deficit spending spree. Not only has America become habituated to deficit spending, debt (including personal debt), and assorted forms of entitlement. How many people volunteer nowadays to pay sufficiently more taxes to solve- or at least significantly reduce- near term (as well as long run) national fiscal troubles? For a debtor nation such as America, running substantial budget deficits alongside elevated (and thus expanding) government debt as a percentage of nominal GDP raises the risk of a severe fiscal trial. The arrival of this crisis probably will occur relatively soon rather than at some vague date many years down the road. In any event, this visit will tend to raise US government rates. The US may be an economic fortress, but that does not guarantee that its creditworthiness will be unquestioned or unchallenged. Witness Europe in recent years; also recollect the debt sagas of many emerging marketplaces.

What are key levels for the US Treasury 10 year note? Start at the low end and walk higher.

FOLLOW THE LINK BELOW to download this market essay as a PDF file.
Fed Fixations- Interest Rates (9-24-12)
US Treasury 10 Year Note Chart (9-24-12)

FINANCIAL FOREST FIRES: US GOVERNMENT DEBT (c) Leo Haviland August 15, 2012

The United States Federal Reserve Board and its central banking allies have furiously battled the fierce financial forest fires of the ongoing worldwide economic crisis that emerged five years ago. As the disaster developed and traveled across the financial landscape, their accommodative approaches evolved. Although central bank methods have varied to some extent, they generally have included deluges of money printing and pinning nominal policy rates (Federal Funds and so forth) close to the ground. These central bank actions not only helped to spark and sustain economic recovery, but also bought politicians time to solve, or at least substantially mitigate, troubling fiscal deficit problems.

Nevertheless, debt levels and deficit spending in America and many other countries generally remain substantial. Efforts targeted to assist recovery partly explain the size of gaping fiscal deficits of recent years. Yet in America and many other nations, they arguably reflect and are structurally sustained by a culture of entitlement. This culture, although not universally shared, extends across the economic spectrum. In any event, government budget deficits in the United States are not a new phenomenon.

However, even without specifically concentrating on its long term fiscal challenges, the US probably is much closer these days to a big debt problem than many believe. Focusing on the near term US government deficit and debt situation in the context of several other nations highlights the danger.

Everyone knows of the Eurozone (Euro Area) crisis. America’s fiscal balances are much more in deficit over the 2008-2017 span than the overall Euro Area’s.

However, from the general government gross debt viewpoint, and especially with a view on 2012 and thereafter, the US problem looks at least as fearsome as the overall Eurozone difficulty. First, the US level exceeds the European height every year, from 2008 out to 2017. Second, the IMF indicates a fall for the Euro Area after 2013, but not for the US.

Inflation is not the only potential source of higher interest rates. The lesson of the Eurozone sovereign debt crisis shows that government interest rates can climb sharply in crisis nations (Greece, Portugal, Ireland, Spain, Italy) even if inflation is moderate. Ability to pay debts (and borrow money), not just inflation levels and trends, matters for interest rate levels (and sovereign credit spread differentials). A badly stretched debtor may have to pay up to find money, right? So rising government interest rates in some cases may reflect a dreadful debt crisis, not a sunny economic recovery.

Closely nearing or reaching a point of no return on the US fiscal front therefore probably would be reflected by a spike in UST yields. The 10 year US Treasury note offers a benchmark for US yield watchers. In recent years, rising government interest rates often have been roughly tied to ascending US stocks (S+P 500), not just an economic recovery. If US equity benchmarks such as the S+P 500 start to decline significantly, and roughly “alongside” the increase in yields (thereby breaking from the guideline UST/stock relationship of recent times), that probably would confirm the existence of a debt crisis.

FOLLOW THE LINK BELOW to download this market essay as a PDF file.
Financial Forest Fires- US Government Debt (8-15-12)
US Treasury 10 Year Note Chart (8-15-12)