

GLOBAL ECONOMICS AND POLITICS

Leo Haviland provides clients with original, provocative, cutting-edge fundamental supply/demand and technical research on major financial marketplaces and trends. He also offers independent consulting and risk management advice.

Haviland’s expertise is macro. He focuses on the intertwining of equity, debt, currency, and commodity arenas, including the political players, regulatory approaches, social factors, and rhetoric that affect them. In a changing and dynamic global economy, Haviland’s mission remains constant – to give timely, value-added marketplace insights and foresights.

Leo Haviland has three decades of experience in the Wall Street trading environment. He has worked for Goldman Sachs, Sempra Energy Trading, and other institutions. In his research and sales career in stock, interest rate, foreign exchange, and commodity battlefields, he has dealt with numerous and diverse financial institutions and individuals. Haviland is a graduate of the University of Chicago (Phi Beta Kappa) and the Cornell Law School.


Subscribe to Leo Haviland’s BLOG to receive updates and new marketplace essays.

RSS View Leo Haviland's LinkedIn profile View Leo Haviland’s profile



CRITICAL CONDITIONS AND ECONOMIC TURNING POINTS © Leo Haviland February 5, 2020

“Just Dropped In (To See What Condition My Condition Was In)”, a Mickey Newbury song performed by Kenny Rogers

****
CONCLUSION

With the passage of time following 2007-09’s global economic disaster, memories regarding the accompanying bloody bear trend in America’s stock marketplace benchmarks such as the S+P 500 gradually yet significantly faded. As the S+P 500 ascended, and especially as it advanced to and sustained record highs, widespread sermons declared that we should “buy the dip”. This aligned with the venerable proverb regarding the reasonableness of buying and holding United States stocks for the “long run”. What constitutes a “dip” or the “long run” is debatable, a matter of subjective perspective (opinion). How substantial a drop from some key elevation justifies buying? Is it one percent, five percent, ten percent, or twenty percent or greater? Is the long run one year, five years, or ten or more?
Of course since the S+P 500’s major bottom on 3/6/09 at 667, a few bloody stock price slides in that signpost (and “related” global equity yardsticks) terrified stock “investors” and their allies, including central banks such as the Federal Reserve, American politicians, and the financial media. Yet as the S+P 500 achieved a record height quite recently with 1/22/20’s 3338 (2/5/20’s level matched this), such advice definitely looked excellent to many stock owners and observers! Besides, as they have numerous times over the past eleven years, won’t beloved central bank physicians such as the Federal Reserve Board (under the guise of fulfilling their mandate), European Central Bank, the Bank of England, China’s central bank, and the Bank of Japan rescue stocks and generate rallies in them? Not only soothing rhetoric, but also yield repression and quantitative easing (money printing) remain antidotes for stock price drops, right? And politicians might assist via new tax cuts, boosts in infrastructure spending, or similar schemes. Thus the majority of US stock marketplace players have focused more on the rewards of owning than the dangers of doing so. Substantial complacency reigns regarding the potential for noteworthy American and other stock marketplace price declines.

****

The recent emergence within China of a deadly coronavirus and its spread elsewhere around the globe helped to push US and other equities downhill. Whether this medical problem will injure the S+P 500 and other global stocks significantly (and for a sustained period of time) remains uncertain. Government actions to prevent the spread of the virus will tend to hamper economic growth. Fearful consumers and nervous corporations may slow their spending. The wider the reach and the longer the persistence of the ailment, the greater the economic damage. And economic (financial) weapons such as money printing and yield repression available to the Fed and its friends obviously do not halt epidemics or cure diseases (or fears of them).Though the S+P 500 descended to 3215 on 1/31/20, the index recovered, touching 3338 again on 2/5/20.

FOLLOW THE LINK BELOW to download this article as a PDF file.
Critical Conditions and Economic Turning Points (2-5-20)
AMERICAN HOUSING: A MARKETPLACE WEATHERVANE © Leo Haviland December 4, 2018

“What You Own”, a song from the musical “Rent” (by Jonathan Larson), declares: “You’re living in America at the end of the millennium- you’re living in America, where it’s like the twilight zone.”

****

OVERVIEW AND CONCLUSION

American home prices have enjoyed a joyous climb since their dismal lows following the global economic disaster of 2007-09. However, United States home prices “in general” (“overall”) now probably are establishing an important peak. At least a modest reversal of the magnificent long-run bullish United States home price trend probably is near.

What is a high (too high), low (too low), expensive, cheap, average, good, bad, neutral, normal, typical, reasonable, commonsense, appropriate, fair value, overvalued, undervalued, natural, equilibrium, rational, irrational, or bubble level for prices or any other marketplace variable is a matter of opinion. Subjective perspectives differ. In any case, current US home price levels nevertheless appear quite high, particularly in comparison to the lofty heights of the amazing Goldilocks Era. As current American home price levels (even if only in nominal terms) hover around or float significantly above those of the Goldilocks Era, this hints that such prices probably are vulnerable to a noteworthy bearish move. Moreover, measures of global home prices and US commercial real estate also have surpassed their highs from about a decade ago and thus arguably likewise may suffer declines.

Many United States housing indicators in general currently appear fairly strong, particularly in relation to their weakness during or in the aftermath of the global economic crisis. Nevertheless, assorted American housing variables as well as other phenomena related to actual home price levels probably warn of upcoming declines in American home (and arguably other real estate) prices. A couple of US home price surveys have reported price declines for very recent months. US housing affordability has declined. New single-family home sales display signs of weakness, as do new privately-owned housing starts. American government interest rate yields, as well as US mortgage rates, have edged up. The Federal Reserve Board as of now likely will continue to tighten and raise rates for a while longer. Overall household debt, though not yet burdensome (at least for many), now exceeds the pinnacle reached ten years ago in 3Q08. The economic stimulus from America’s December 2017 tax “reform” probably is fading. US consumer confidence dipped in November 2018.

Marketplace history of course does not necessarily repeat itself, either entirely or even partly. Convergence and divergence (lead/lag) relationships between marketplace trends and other variables can shift or transform, sometimes dramatically. Price and time trends for the American stock marketplace and US housing prices do not move precisely together. However, the international 2007-09 crisis experience (which in part strongly linked to US real estate issues) indicates that prices for US stocks and housing probably will peak around the same time, or at least “more or less together” (a lag of several months between the stock high and the home price pinnacle). The S+P 500 probably established a major high in autumn 2018 (9/21/18 at 2941, 10/3/18 at 2940; the broad S&P Goldman Sachs Commodity Index peaked 10/3/18 at 504). That autumn equity summit in the S+P 500 bordered 1/26/18’s interim top at 2873. Ongoing weakness in US (and international) stock marketplaces will help to undermine American home prices.

FOLLOW THE LINK BELOW to download this article as a PDF file.
American Housing- a Marketplace Weathervane (12-4-18)

GOLD AND GOLDILOCKS: 2017 MARKETPLACES © Leo Haviland, January 10, 2017

“I think I’ll go to sleep and dream about piles of gold getting bigger and bigger and bigger.” Fred C. Dobbs, in the 1948 movie, “The Treasure of the Sierra Madre” (John Huston, director)

****

CONCLUSION

The extent to which important financial playgrounds intertwine and their alleged trends converge or diverge (or, lead or lag) are matters of opinion, as are perspectives on and reasons for such relationships and movements. Apparent convergence/divergence and lead/lag patterns between currency, interest rate, stock, and commodity marketplaces nevertheless offer guidance to players seeking to explain, predict, or profit from financial price movements. Marketplace history need not repeat itself, either entirely or even in part. Thus these relationships can change, sometimes dramatically. Fundamental supply/demand factors and trends are not written in stone. And competing historians and clairvoyants do not necessarily share the same perspectives or tell the same stories regarding either a given financial playground or its relationships to other arenas.

The relationships between gold and the US dollar, as well as those between gold and other commodities and stock and interest rate marketplaces, are complex. Often, gold prices travel in roughly similar fashion to those of base metals in general and the overall petroleum complex. Yet sometimes substantial fears regarding financial meltdown (asset value destruction) or striking worries about political evolution or disruption also can influence gold’s supply/demand and price profile, and thereby gold’s interrelations with commodities as well as currency and securities marketplaces. In any case, significant gold price trend changes often precede or roughly coincide (or “confirm”) those elsewhere.

Gold probably established an important low not long ago, at $1124 on 12/15/16. Suppose this gold rally continues for at least the near term. The gold ascent probably warns of peaks in the broad real trade-weighted United States dollar (“TWD”) and the S+P 500. The current divergence between the S+P 500 and emerging marketplace nation stocks in recent months likewise warns of these trend shifts. Relevant to this viewpoint, the 10 year United States Treasury note yield established a major low at 1.32 percent on 7/6/16. In addition, suppose gold’s recent climb eventually coincides with a renewed slump in the LMEX base metals index (London Metal Exchange) from its 11/28/16 top at 2857, and at least a modest tumble in benchmark petroleum prices. That probably will interrelate with this scenario of US dollar weakness and erosion of S+P 500 and emerging marketplace stock prices.

The American political theater is relevant to this outlook for gold price and its relationship to the US dollar and other marketplaces. Trump’s remarkable Presidential victory and his likely policies probably have increased fears in both American and international domains regarding the quality of America’s political leadership and the consequences of its economic (political) philosophy. Moreover, the nation’s various sharp cultural divisions and related partisan political conflicts will not disappear anytime soon.

FOLLOW THE LINK BELOW to download this article as a PDF file.
Gold and Goldilocks- 2017 Marketplaces (1-10-17)

COMMODITIES AND US STOCKS: CONVERGENCE AND DIVERGENCE © Leo Haviland January 28, 2013

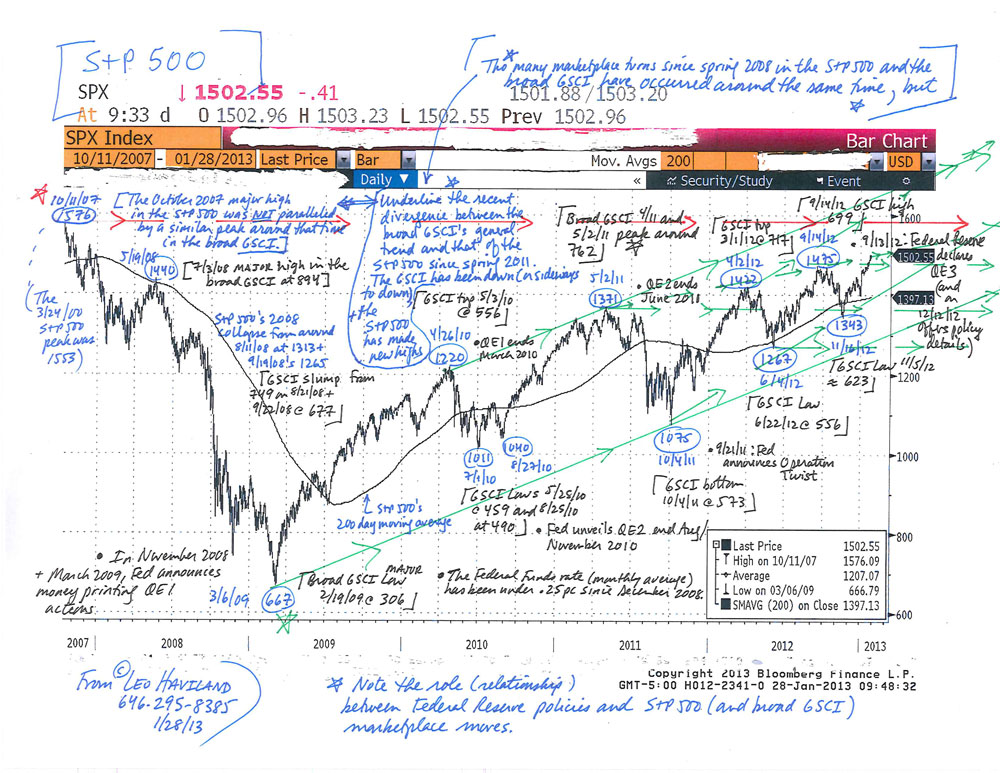
Since mid-2008, commodities “in general” and United States stocks “as a whole” have moved roughly in the same direction at around the same time. In this convergence process (relationship), noteworthy bull (bear) moves in US equities find parallels in those in the commodity arena. Thus significant marketplace rallies (declines) have tended to occur around the same time.

However, this perspective is not the only vantage point by which to assess the often close relationship between US equities and the commodities complex. There also is another, longer run view by which one can examine the relationship between them. Since spring 2011, commodities have ventured down (or sideways to down). However, key American stock benchmarks such as the S+P 500 have attained new highs, first in April 2012, then September 2012, and again in January 2013. Thus despite the convergence at assorted timely turning points since spring/ summer 2008, and even though the two territories continue to trade together to some extent, arguably there has been noteworthy divergence in their overall relationships (their trends) since May 2011.

Now recall several of 2007-08’s details. US equities peaked in October 2007, almost nine months before the commodity one in early summer 2008. Only after the final stock marketplace

summit in May 2008 did equities and commodities trade in close tandem. The current longer run relationship thus perhaps likewise reveals divergence, but with the commodity peak to date appearing well before any major S+P 500 one.

In contrast to 2007-08, what if the major peak in commodities is well before that in stocks (and the lag is likewise so great as to suggest divergence)? Suppose- and this admittedly is a key suppose- eventually commodities and US stocks will trade together over the long run. After all, so-called marketplace relationships can change dramatically, whether from the convergence/ divergence (lead/lag) perspective or otherwise. What does continued divergence, the failure of commodities to near or exceed its spring 2011 heights, suggest?

The 2007-08 relationship warns that the current continued failure of commodities to confirm the equity rally eventually will reveal a notable decline in stocks. Since the duration between the spring 2011 commodities top and today’s new highs in the S+P 500 is almost 20 months, whereas that between October 2007’s stock pinnacle and the broad GSCI’s summit in July 2008 was about nine months, the failure of the broad GSCI to achieve new heights should warn equity bulls that a decline may be fairly near in time.

S+P-500-Chart-(1-28-13,-for-essay-on-Commodities-and-US-Stocks)

FOLLOW THE LINK BELOW to download this market essay as a PDF file.
Commodities and US Stocks- Convergence and Divergence (1-28-13)
S+P 500 Chart (1-28-13, for essay on Commodities and US Stocks)