GLOBAL ECONOMICS AND POLITICS

Leo Haviland provides clients with original, provocative, cutting-edge fundamental supply/demand and technical research on major financial marketplaces and trends. He also offers independent consulting and risk management advice.

Haviland’s expertise is macro. He focuses on the intertwining of equity, debt, currency, and commodity arenas, including the political players, regulatory approaches, social factors, and rhetoric that affect them. In a changing and dynamic global economy, Haviland’s mission remains constant – to give timely, value-added marketplace insights and foresights.

Leo Haviland has three decades of experience in the Wall Street trading environment. He has worked for Goldman Sachs, Sempra Energy Trading, and other institutions. In his research and sales career in stock, interest rate, foreign exchange, and commodity battlefields, he has dealt with numerous and diverse financial institutions and individuals. Haviland is a graduate of the University of Chicago (Phi Beta Kappa) and the Cornell Law School.


Subscribe to Leo Haviland’s BLOG to receive updates and new marketplace essays.

RSS View Leo Haviland's LinkedIn profile View Leo Haviland’s profile


US NATURAL GAS: THE 2013 BUILD UP © Leo Haviland April 25, 2013

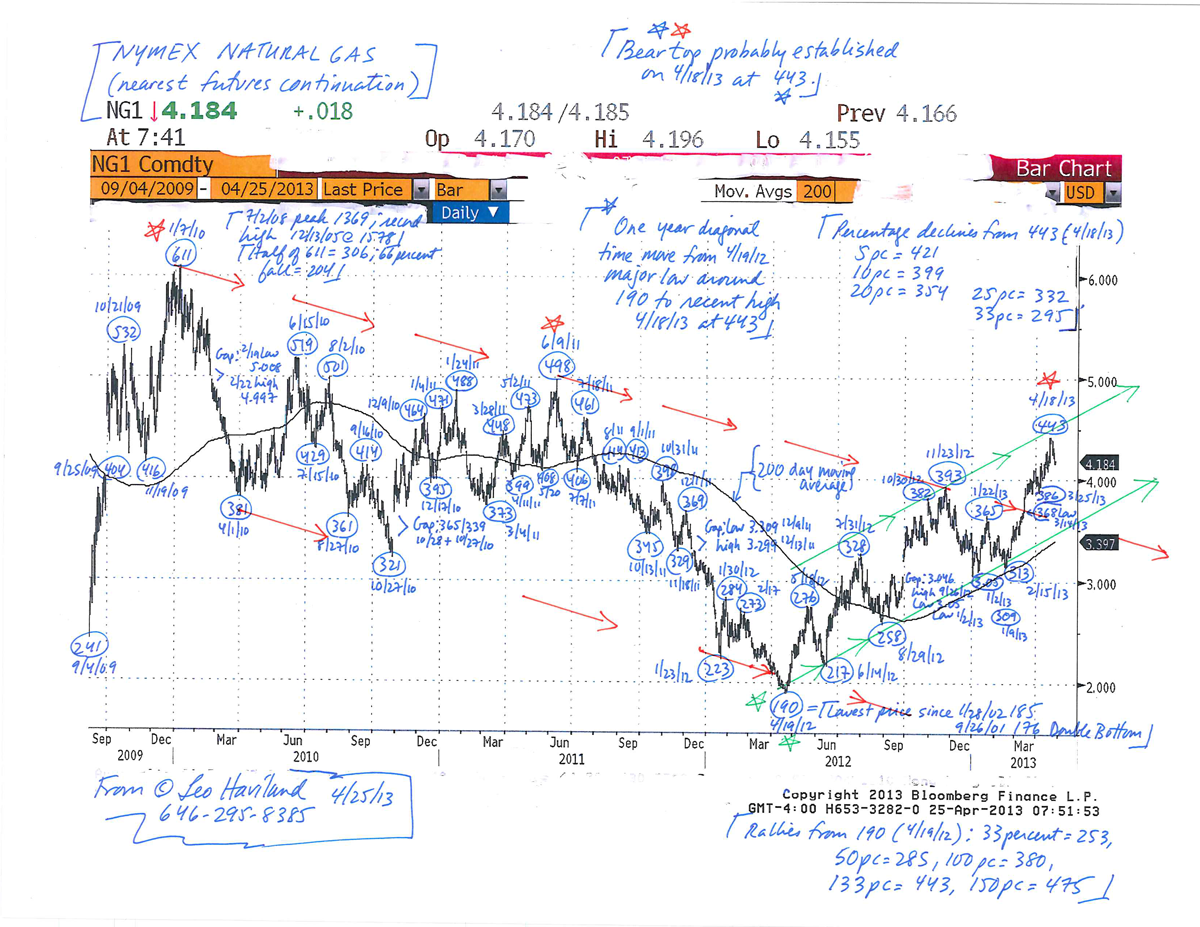
Assuming normal weather, the United States natural gas inventory situation probably will remain around average levels (1990-2012 history) in days coverage terms as the April/October 2013 build season marches forward. Yet if NYMEX prices (nearest futures continuation basis) persist over 400, there is a modest risk that over the next several months greater stock increases than many forecasters predict will occur. In any event, even based on current Energy Information Administration (EIA) supply/demand estimates, by the end of winter 2013-14 draw season, US natural gas days coverage probably will be moderately above average. Also, not only has the major bull move from the dismal April 2013 bottom around 190 (4/19/13) to recent highs around 443 (4/18/13) been enormous (about 133 percent); it has been lengthy in time (a one year diagonal time move).

So what is the near term outlook for US natural gas prices (nearest futures continuation)? They probably will retreat further from around the levels reached in mid-April 2013. A 20 percent decline gives around 354; important support exists around the 305/310 1Q13 lows. What about the mystical time horizon called the long run? Suppose weather is normal and the American economy grows moderately. The longer run natural gas trend probably will be sideways, with the broad range roughly 280/310 to 490/520.
Natural-Gas-Chart-(NYMEX-nearest-futures)-(4-25-13)

FOLLOW THE LINK BELOW to download this market essay as a PDF file.
Natural Gas Chart (NYMEX nearest futures) (4-25-13)
Natural Gas- the 2013 Build Up (4-25-13)

US OVERALL PETROLEUM INVENTORIES- ENOUGH IS ENOUGH © Leo Haviland April 5, 2013

What does a survey of total United States petroleum industry inventories (crude and products combined) relative to total products supplied indicate regarding current and near term US petroleum price trends? The very elevated days coverage (end month inventories versus average daily consumption for that calendar month) probably has significantly contributed to the renewed price weakness in the overall petroleum complex that emerged in February 2013.

The broad GSCI established a major high around 762 in spring 2011 (4/11 and 5/2/11 tops), with lower peaks at 717 on 3/1/12 and 699 on 9/14/12. NYMEX crude oil (nearest futures continuation) peaked 5/2/11 at 11483, with lower tops on 3/1/12 at 11055 and 9/14/12 at 10042.

As part of the major longer run downtrend that exists for commodities in general, note the assortment and timing of minor tops made in early 2013 (especially February) in several commodity indices and in numerous particular commodity marketplaces.

Many watch US equities alongside commodities in general and petroleum prices in particular. The S+P 500 in the past three years made springtime highs: 4/26/10 at 1220, 5/2/11 at 1371, and 4/2/12 at 1422. Compare the timing of the high in the S+P 500 during its recent rally, 4/2/13 at 1574. Compare also this 4/2/13 high in the S+P 500 with the timing of the fall off points in the petroleum complex just noted, as well as the renewed tumble in the broad GSCI from its 3/28/13 level around 659.

FOLLOW THE LINK BELOW to download this market essay as a PDF file.
US Overall Petroleum Inventories- Enough Is Enough (4-5-13)

US NATURAL GAS: THE WINTER INVENTORY DRAWING BOARD © Leo Haviland October 1, 2012

Having established a major low at 190 on 4/19/12 (NYMEX nearest futures continuation), natural gas marched sharply higher, reaching significant resistance around 330 (7/31/12). After retreating to 258 (8/29/12), the marketplace renewed its assault on the 330 barrier in late September. Even if prices lose some ground in the near term, and assuming normal weather, a decisive advance above that level, and to at least major resistance hovering at 380 to 415, probably will occur in the next few months. It would not be surprising if the initial assault on 380/415 occurred relatively soon.

But why will prices keep climbing? Admittedly, bears have good arguments. For example, current United States natural gas inventories (9/21/12 stocks of 3576bcf) are up about nine percent year-on-year. Suppose weather is around average for the 2012-2013 winter draw season. An initial review of United States natural gas inventories from a days coverage perspective indicates oversupply for the upcoming draw season.

However, there arguably is less oversupply in the near term than many believe. There seems to have been an upward shift in desired stockholdings from the days coverage vantage point in recent years.

In addition, inventories during winter and at end season 2012-13 probably will be far less excessive than during the preceding draw season. This will tend to excite many bulls.

For the next few months, natural gas production growth appears to be flattening (compare calendar 2012 with 2013). But gas demand increases, assuming sustained higher prices over 330, and maybe a bit cheaper, also may level off.

Yet it seems that natural gas is “looking forward” over a longer horizon than just the next few months (or maybe even calendar 2013). A bullish aura underpinning natural gas “for the long run” derives significantly from the coal plant retirement story (especially in 2014 and thereafter). This enthusiasm (though it may eventually confront supply jumps) thus thereby assists to some extent the bullish near term price trends. Also, nuclear power supplies probably will not increase much anytime soon; some players question how much and how quickly renewable supply will blossom from here.

This longer run bullish natural gas faith (orientation) has an implication for the probable willingness of natural gas producers to short hedge, say at around 380/415, or even 450 and beyond (strategies surely differ for each calendar year). Short hedging at these levels probably will be less than many believe.

What about LNG? The extent of LNG exports is conjectural. However, at quite low prices (picture under 200, maybe even 250), the export appeal rises. Though these floors are much beneath current prices, this story tends to support the upward price bias established in April 2012.

Add a technical bull point from the timing perspective. Many key natural gas (NYMEX nearest futures) marketplace bottoms have been reached in late August and calendar September. This did not occur in calendar 2012, which argues that the new highs being made recently will be surpassed. Also, the minor low around 258 in late August, although not close to the April 2012 depth, nevertheless occurred at a time from which prices often have sprung higher. Thus the quick travel higher of the past several weeks argues for a further upward flight.

FOLLOW THE LINK BELOW to download this market essay as a PDF file.
Natural Gas- the Winter Inventory Drawing Board (10-1-12)


US NATURAL GAS: BURNING UP (c) Leo Haviland July 23, 2012

Focus on natural gas days coverage levels for end October 2012 (around the close of inventory build season) and end March 2013 (approximate end of draw period) in the context of price history. Assume normal weather and relatively lofty petroleum prices. What does this perspective reveal? This not only indicates that April 2012’s 190 was a major low and that major support exists around 220/240 (NYMEX nearest futures continuation). It also justifies a challenge on significant resistance around 317/330. An ascent above that range sometime in the next several months will be difficult but not surprising.

However, days coverage probably will have to sustain a decline in its excess relative to its long run average (1990-2011) to around three days or fewer for natural gas to significantly challenge major resistance looming around 400. The sustained reduction in days coverage to such levels likely will occur eventually, even if it does not occur by the end of March 2013.

However, the duration of about three months from 4/19/12 to date is about that of the 2010 and 2011 spring rallies. This time element warns that one should be cautious about declaring a further big upward move lies in store for the very near term, especially given the proximity of the 317/337 resistance.

But the 2009/early 2010 period teaches an important lesson for natural gas. It strongly suggests that elimination of containment fears, when followed by a dramatic reduction in days coverage, can help to propel natural gas prices much higher (and perhaps quite quickly). Inventory prospects several months out, not just the current (or very near term), matter.

So from the inventory days coverage standpoint, and particularly when read relative to the 2009 context and its eventual price rally from 241, what follows? This huge reduction in oversupply from March 2012 to October 2012 strongly indicates that there was a major low in April 2012 (not a mere interim bottom), that prices will not easily (if at all) come back to that level, and that a major bull move from that April 2012 low (not a mere interim rally) is underway.

FOLLOW THE LINK BELOW to download this market essay as a PDF file.
Natural Gas- Burning Up (7-23-12)
Natural Gas Chart (NYMEX nearest futures)(7-23-12)