GLOBAL ECONOMICS AND POLITICS
Leo Haviland provides clients with original, provocative, cutting-edge fundamental supply/demand and technical research on major financial marketplaces and trends. He also offers independent consulting and risk management advice.
Haviland’s expertise is macro. He focuses on the intertwining of equity, debt, currency, and commodity arenas, including the political players, regulatory approaches, social factors, and rhetoric that affect them. In a changing and dynamic global economy, Haviland’s mission remains constant – to give timely, value-added marketplace insights and foresights.
Leo Haviland has three decades of experience in the Wall Street trading environment. He has worked for Goldman Sachs, Sempra Energy Trading, and other institutions. In his research and sales career in stock, interest rate, foreign exchange, and commodity battlefields, he has dealt with numerous and diverse financial institutions and individuals. Haviland is a graduate of the University of Chicago (Phi Beta Kappa) and the Cornell Law School.
Subscribe to Leo Haviland’s BLOG to receive updates and new marketplace essays.

What is the near term outlook for United States natural gas prices (nearest futures continuation)? They probably will retreat further from around the ceilings reached in mid-April to early May 2013. A 20 percent decline gives around 356, rather close to the 6/28/13 low at 353. However, assuming normal weather, a breach of 350 probably will be modest. Some support exists around 328, the 7/31/12 high; important support exists around the 305/310 first quarter 2013 level. The most likely time for at least an interim bottom is late August to calendar September 2013.
Why remain somewhat bearish on US natural gas for the near term? After all, natural gas clearly constructed a major low around 190 on 4/19/12, and that floor probably will not be broken anytime soon. Also, US gas inventory in days coverage terms at end October 2013 from the long run (1990-2012) perspective probably will be only slightly above average. Moreover, perhaps the desired levels of natural gas inventory holding have shifted upward in recent years. This is by no means certain, though. In any event, if one selects the 2006-12 horizon as the relevant one, then end October supplies fall modestly below this revised average.
Nevertheless, even if marketplace engineers adopt the 2006-12 vista as the most relevant one for inventory analysis, natural gas stocks at end winter 2013/14 draw season probably will be moderately high relative to average in days coverage terms. In addition, the noncommercial long position in natural gas that helped to propel prices to their spring 2013 heights, though it has slumped in recent weeks, remains substantial. Its liquidation will pressure prices. Despite the neutral (or even slightly bullish) inventory situation in days coverage terms for October 2013, the American supply/demand situation from the production and consumption trend perspective for 2013 (at least the past few months and “nowadays”) and (especially) 2014 on balance is slightly bearish. Demand from the key electric power sector arguably will not jump up in the near term unless prices sustain falls under 350. Notable US LNG exports remain a prospect for the relatively distant future. Overall US electricity consumption growth remains mediocre.
Over the mystical time horizon called the long run, assuming normal weather and moderate American economic growth, the longer run natural gas trend probably is sideways. The broad range stands from roughly 280/310 to 490/520.
Read the rest of this entry »
What does a survey of total United States petroleum industry inventories (crude and products combined) relative to total products supplied indicate regarding current and near term US petroleum price trends? The very elevated days coverage (end month inventories versus average daily consumption for that calendar month) probably has significantly contributed to the renewed price weakness in the overall petroleum complex that emerged in February 2013.
The broad GSCI established a major high around 762 in spring 2011 (4/11 and 5/2/11 tops), with lower peaks at 717 on 3/1/12 and 699 on 9/14/12. NYMEX crude oil (nearest futures continuation) peaked 5/2/11 at 11483, with lower tops on 3/1/12 at 11055 and 9/14/12 at 10042.
As part of the major longer run downtrend that exists for commodities in general, note the assortment and timing of minor tops made in early 2013 (especially February) in several commodity indices and in numerous particular commodity marketplaces.
Many watch US equities alongside commodities in general and petroleum prices in particular. The S+P 500 in the past three years made springtime highs: 4/26/10 at 1220, 5/2/11 at 1371, and 4/2/12 at 1422. Compare the timing of the high in the S+P 500 during its recent rally, 4/2/13 at 1574. Compare also this 4/2/13 high in the S+P 500 with the timing of the fall off points in the petroleum complex just noted, as well as the renewed tumble in the broad GSCI from its 3/28/13 level around 659.
FOLLOW THE LINK BELOW to download this market essay as a PDF file.
US Overall Petroleum Inventories- Enough Is Enough (4-5-13)
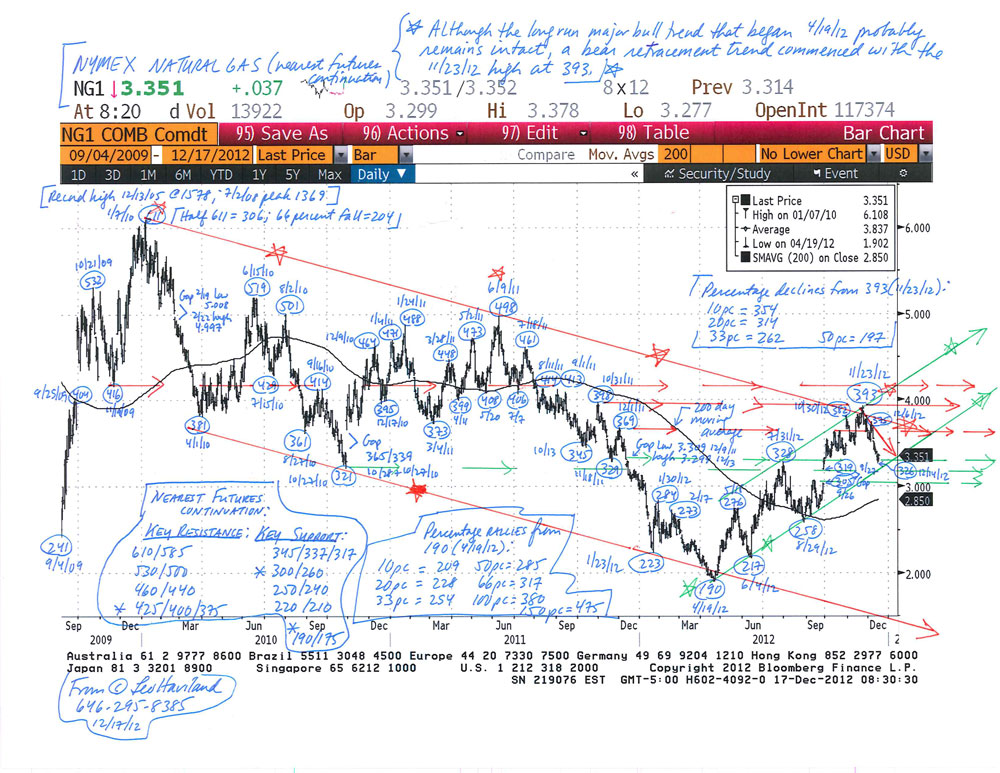
The current bear trend in US natural gas (NYMEX nearest futures continuation basis) that began in late November 2012 at 393 will continue. Assuming normal cold winter weather, the price probably will slump to around the 300 to 285 range. When will the price quit sledding downhill? Though it may only be an initial significant bottom, look for an important low in calendar January or February 2013, probably around futures expiration.
End October 2012 inventories were around 3923bcf according to the EIA barometer (Short-Term Energy Outlook, December 2012; “STEO”). Therefore end October’s 56.3 days of coverage rest about 2.6 days above the 53.7 day long run (1990-2011) average. Though not a big overload relative to that long run average, it is sufficient to place some burden on prices.
Moreover, look at the likely increasing relative oversupply in days coverage terms versus the 1990-2011 average for the given calendar month as time passes from end October 2012 to end March 2013. At end March 2013, forecast inventories of 1873bcf (December STEO, Table 5a) represent about 26.9 days coverage (1873bcf divided by 69.70bcf/d). This jumps about 4.7 days over the 22.2 day long run average for that month, more than October’s 2.6 days.
Suppose end March 2013 inventories are 1800bcf. The excess relative to the long run average is 3.6 days (25.8 less 22.2). This still hovers above the 2.6 day end October 2012 difference.
Despite the ongoing near term downtrend, and absent another very mild winter akin to 2011-12’s, a NYMEX natural gas price collapse close to the 190 abyss of April 2012 (or even the 1/23/12 and 6/14/12 depths near 220) is unlikely.
Based on 2012’s substantial switching from coal to natural gas, particularly in the electric power territory, natural gas demand probably will mount if prices sustain levels beneath (roughly) 275. In addition, another factor probably will mitigate price declines. Concentrate on days coverage holdings in recent years.
The desired level of natural gas inventory holding in recent years arguably has climbed relative to that long run average. Consequently the oversupply of October 2012 through March 2013 probably is less than many observers believe.
FOLLOW THE LINK BELOW to download this market essay as a PDF file.
US Natural Gas in Winter 2012-13- Drawing Conclusions (12-17-12)
Natural Gas Chart (NYMEX nearest futures) (12-17-12)


 View Leo Haviland’s profile